We'd love to hear from you
You can also chat with us or call (949) 450-0202

3 Changes Condo Boards Need to Understand About Fannie Mae and Freddie Mac's New Guidelines
What the 2026 condo lending updates mean for insurance and reserves
3 Changes Condo Boards Need to Understand About Fannie Mae and Freddie Mac's New Guidelines
What the 2026 condo lending updates mean for insurance and reserves
A condominium buyer can walk into a loan application with a strong credit score, a clean history, and every box checked, and still watch the deal fall apart. The problem in that case sits with the association the buyer is trying to join.
That scenario is becoming more common. Fannie Mae and Freddie Mac, the two government sponsored entities that underpin much of the country's mortgage system, have tightened the rules condominium associations must meet to stay eligible for financing. Fannie Mae's Lender Letter LL-2026-03, issued March 18, 2026, and Freddie Mac's companion Bulletin 2026-C set out the changes. For boards and managers who assumed this was a background issue for someone else to track, the stakes just went up.
The short answer: as of 2026, nearly every condo loan now triggers a full review of the association's finances, and three changes drive most of the risk in that review. They involve insurance requirements, reserve studies, and reserve contributions.
Why Fannie Mae and Freddie Mac Rules Affect Associations That Never Use Them
Here is the part that surprises a lot of board members. Many condominium associations rarely see a Fannie Mae or Freddie Mac backed loan. Plenty of buyers in higher priced communities use private financing instead, so it would be reasonable to assume those associations are free of the guidelines.
They are not. Private lenders lean heavily on Fannie Mae and Freddie Mac standards as a benchmark for risk, even on loans those two entities will never hold. If a lender's underwriting mirrors federal guidance, an association that falls short can still see a loan denied.
The effect lands hardest on condominiums. Single family homes rarely run into this issue. With a condo, the health of the overall association is part of what a lender evaluates, right alongside the individual unit.
The End of the Limited Review
For years, lenders used two levels of condo project review. A full review was the thorough version, examining the association's budget, reserve status, and any deferred maintenance. A limited review was the default for most closings in established projects. It was quicker and narrower, and it focused mainly on the buyer and the unit.
LL-2026-03 retired the limited review. For conventional loan applications dated on or after August 3, 2026, established projects with more than 10 units go through the full review process. (Smaller projects of 10 or fewer units may qualify for a waiver of project review.) That puts the budget, reserves, insurance, and deferred maintenance history of the entire association on the table for nearly every transaction.
In practical terms, the buyer has to qualify for their own financing, and then the association has to qualify separately. A buyer with a flawless financial picture can still be denied because of a reserve shortfall or an insurance gap that has nothing to do with them personally.
1. Insurance Requirements: Replacement Cost Over Actual Cash Value
One of the clearest changes involves insurance. Associations used to be able to carry coverage based on actual cash value, a figure that accounts for depreciation. A twenty year old balcony might only be worth a fraction of what it would cost to rebuild, and actual cash value coverage reflected that lower number.
That approach no longer works for most components. Coverage now has to reach 100% of the replacement cost of the association's capital improvements. If a casualty event destroys a set of balconies that would cost $50,000 to rebuild, the policy has to cover the full $50,000. Roofs remain the one carved out exception.
Full replacement coverage costs more than depreciated coverage, so premiums are likely to rise. There is a quieter issue worth watching too. The insurance carrier typically sets the replacement cost valuation, and a higher valuation drives a higher premium. Boards that want to confirm they are paying for the right number can ask their insurance broker about a third party valuation.
Deductibles are now capped at $50,000 per unit, which limits the option of offsetting higher premiums with a much larger deductible.
Takeaway: Ask your insurance broker to compare your current master policy against the updated requirements before your next renewal.
2. Reserve Studies and What "Fully Funded" Means
Reserve studies now have to be updated at least every 36 months to meet the guidelines. In California, this lines up closely with Civil Code §5550, which already requires a reserve study with a visual inspection at least once every three years. Texas has no comparable statewide schedule, so Texas condo associations now have a federal timing requirement to meet even though state law never imposed one.
The term "fully funded" trips up a lot of board members. Most reserve studies report a percent funded figure between 0% and 100%, showing how much of the ideal reserve balance the association currently holds. Under the Fannie Mae and Freddie Mac guidelines, "fully funded" refers to something else.
Here, an association is fully funded when it contributes the full amount its reserve analyst recommends, using the highest of the funding methods the analyst presents. The term describes the association's contribution level. An association with a modest percent funded number can still satisfy the requirement, as long as it is putting in what the study says to put in.
Takeaway: Check the date on your most recent reserve study and confirm your budget contribution matches the highest funding recommendation in it.
3. Reserve Contributions: The Floor Moved From 10% to 15%
The third change raises the baseline contribution. Associations now need to direct at least 15% of their annual budgeted assessment income into reserves, up from the previous 10%.
There is an important exception. If an association already fully funds its reserves at the level its reserve study recommends, and that figure happens to fall below 15%, the association still meets the requirement. It does not have to hit both standards. It has to meet whichever one applies to its situation.
For a board building next year's budget, this is the number to watch. An association contributing 11% of assessment income with no reserve study to support that figure may need to revisit its budget before the next buyer applies for a loan.
Is the "Blacklist" Gone?
Board members sometimes describe associations as being on a Fannie Mae or Freddie Mac "blacklist," meaning every loan in that community gets denied. With every loan now going through a full review, there is a fair argument that the old in or out concept no longer applies the same way.
A track record still matters, though. An association with a steady history of approvals is likely to move through reviews more smoothly. One with a mixed or troubled history may draw closer scrutiny from reviewers working through a growing backlog.
When a Loan Gets Denied
If a unit's loan application comes back denied, the buyer's agent may be able to find a private lender willing to finance outside the Fannie Mae and Freddie Mac framework, sometimes at a less competitive rate. Separately, the association should find out exactly why the denial happened. From there, the board can work with its reserve company, management team, and legal counsel to correct the underlying issue before the next application comes through.
Accurate Reporting Protects Everyone
Every one of these reviews depends on information the association or its management company reports to a lender. When that information is wrong, in either direction, it creates exposure. Overstating the association's condition risks a misrepresentation claim. Painting a rosier picture to smooth over a review carries the same risk.
The fix is straightforward. Whoever completes lender questionnaires on behalf of the association needs current, accurate records and a clear process for answering every time.
What the New Fannie Mae and Freddie Mac Guidelines Mean for Your Board
The lender letter behind these changes runs only about nine pages, and some ambiguity remains. Management companies, reserve specialists, and associations are still working out how the finer points will apply in practice. That uncertainty makes the fundamentals more important. Accurate insurance valuations, a current reserve study, and contributions that meet the funding standard can decide whether a buyer closes on a home.
If your association has not reviewed its insurance valuation, reserve study timeline, or contribution level against the new Fannie Mae and Freddie Mac guidelines, now is a good time to start. This article is general information. Your management team, reserve specialist, insurance broker, and association attorney can help with questions specific to your association.
Check out Episode 102 of The Uncommon Area with attorney Clint Brown of RMWBH Attorneys & Counselors at Law to learn more about the new Fannie Mae and Freddie Mac condo guidelines! For more on reserve studies and percent funded, listen to Episode 101.




Check out our podcast library
Check out podcast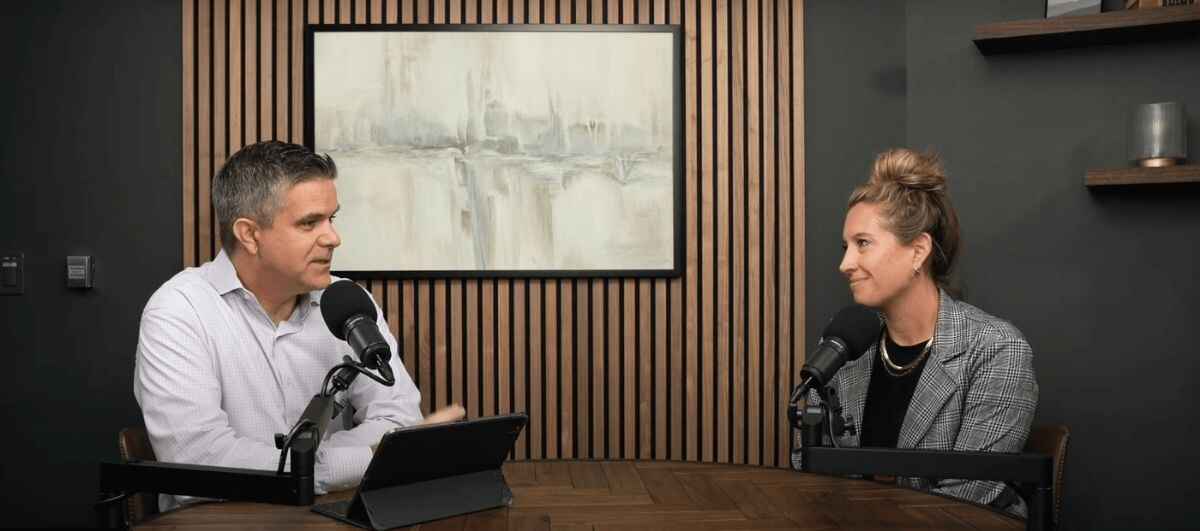


Suite 200
Irvine, CA 92602